Services Financiers AG - Financial security advisor in Quebec.
CORPORATE INSURANCE

Protect your business
with your company's funds.

Corporately held life, disability and critical illness insurance - tailored strategies for entrepreneurs and small business owners in Quebec.

Talk to an advisor
Regulator and partners
Autorité des marchés financiers - AMF
iA Groupe financier, partenaire de Services Financiers AG.
Cabinet MRa, partenaire de Services Financiers AG.
Autorité des marchés financiers - AMF
iA Groupe financier, partenaire de Services Financiers AG.
Cabinet MRa, partenaire de Services Financiers AG.
OUR STRATEGIES

Corporate strategies
suited to your structure.

Whether you're a sole owner or have partners, Alexandre analyzes your company's structure before recommending a strategy that fits, both tax-wise and operationally.

See all our strategies
Company funds
The company pays the premium with funds taxed at the corporate rate, generally lower than your personal rate. The real cost may be lower, depending on your situation.
Capital dividend account
On death, the capital received by the company, minus the policy's adjusted cost basis, is generally added to the CDA and can be paid to shareholders as a tax-free dividend.
Succession plan
A shareholder agreement funded by insurance to support continuity in case of death or disability.
Structure analysis
Alexandre assesses your tax situation before recommending a strategy, to be confirmed with your accountant.
CORPORATE STRATEGIES

All our corporate solutions

Key person

Corporate life insurance

The company owns the policy, is its beneficiary and pays the premium with its own funds. The capital is paid to the business to support its continuity.

  • Capital dividend account (CDA), per tax rules
  • Protection of the business's value
Product page
Succession plan

Corporate critical illness

Helps the business cope with the serious illness of a partner or leader. A lump sum is paid on diagnosis of a covered illness, per the contract.

  • Use of the amount left to the company
  • Insured shareholder agreement
Product page
Taxation

Disability for entrepreneurs

Replacement of part of the entrepreneur's income if disability prevents them from working. The tax treatment of premiums and benefits depends on who pays and on your structure; confirm with your accountant.

  • Own-occupation definition offered per the contract
  • Tax treatment depends on your structure
Product page

Is your business protected if you can no longer work?

A first conversation with Alexandre costs nothing.

Talk to an advisor
WHY ALEXANDRE

Why choose Alexandre
for your corporate insurance?

Alexandre won't recommend a product before understanding your corporate structure, your shareholder agreement and your tax goals. No generic solution.

Learn more about our approach
Structure analysis
Assesses your tax situation and structure before recommending a strategy.
iA Financial Group partner
Access to iA Financial Group products and MRa products, to offer you protection that fits your budget.
Annual follow-up
Review of your strategy every year as your business evolves.
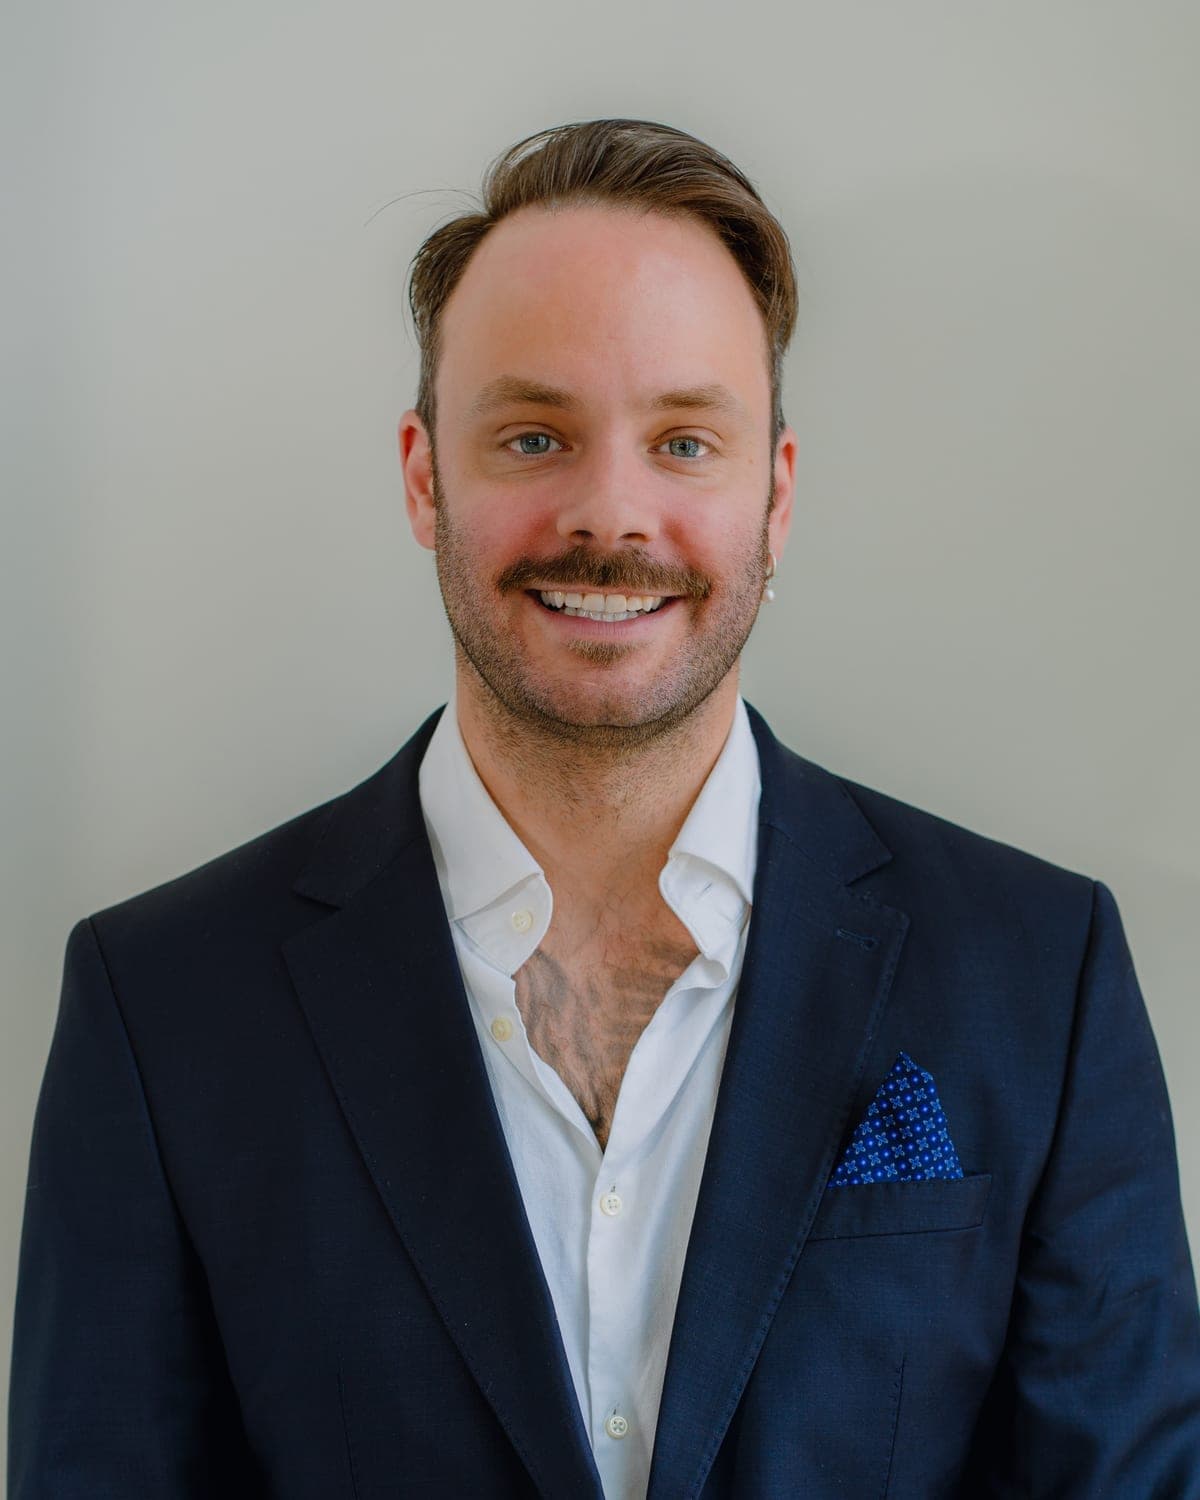
Alexandre Garneau, Financial Security Advisor - Services Financiers AG
FAQ

Your questions about corporate insurance

What is corporately held insurance?
Corporately held insurance means the company owns the policy and pays the premium, rather than the individual. The premium is paid with company funds, taxed at the corporate rate, which may reduce the real cost of coverage depending on your situation. Life insurance premiums are generally not deductible for the company. On death, the capital is paid to the company; the portion above the policy's adjusted cost basis is generally added to the capital dividend account (CDA), from which it can be paid to shareholders as a tax-free dividend. Confirm with your accountant.
What's the difference between key person insurance and a succession plan?
Key person insurance protects the business against the loss of a leader essential to its operations. The succession plan aims to ensure continuity during a change of ownership - often used between partners to allow the buyback of shares in case of death or disability of a partner.
Is disability insurance deductible for an entrepreneur?
It depends on who pays the premium. If you personally pay for your individual disability insurance, the premium is generally not deductible and the benefits are generally not taxable. If your company pays the premium, other rules apply: a taxable benefit is possible and the benefits may become taxable. The tax treatment depends on your situation; Alexandre reviews your structure with you, to be confirmed with your accountant.
When should I set up a corporate strategy?
Ideally as soon as the business generates stable revenue and you have a key shareholder or leader to protect. Premiums are generally lower when you sign up young and healthy. Alexandre looks at the right timing with you based on your situation.
Do my partners need to be involved in the process?
If you have partners, it's strongly recommended to plan together - especially for an insured shareholder agreement. Alexandre can meet all the partners to structure a fair solution consistent with the existing or future agreement.
Your question isn't listed? Contact us →
CORPORATE ANALYSIS

Let's analyze your structure together.

No obligation, directly with Alexandre, Financial Security Advisor, AMF certificate no. 272275. The analysis is free for you. It may lead to a product recommendation; if you buy, Alexandre is paid a commission by the insurer.

Structure analysis included
No obligation to buy
AMF certificate no. 272275 · iA Financial Group

An email or a phone number is enough.

Confidential. Used only to answer your request.