Services Financiers AG - Financial security advisor in Quebec.
CLIENT PROFILE

Are you a
business owner?

Your business is your wealth. If you pass away or can no longer work, everyone around you - partners, employees, family - bears the consequences. Alexandre helps you secure what you've built.

Business owner entrepreneur - Services Financiers AG corporate insurance.
BusinessShareholderCorporate
Incorporated company
Partner shareholder(s)
Employees and obligations
Income through the company
FREE CORPORATE ANALYSIS

Is your business really
protected?

Alexandre reviews your situation and calls you back with a personalized recommendation. Free, no obligation.

Analysis of your corporate structure
Identification of shareholder risks
Recommendations suited to your sector

Estimate your coverage

A few details are enough. Alexandre calls you back with a personalized, no-obligation estimate.

Free · No obligation · Confidential

The analysis is free. If you sign up, Alexandre is paid a commission by the insurer or product provider.

YOUR CORPORATE RISKS

The 4 risks your business
can't afford to ignore

Shareholder agreement

Without insurance, buying back a deceased shareholder's shares requires cash the business doesn't always have. Corporate life insurance can fund that buyback.

Share buyback
Capital on death
Funded agreement

Key person protection

If the driving force of your business falls ill or dies, operations, clients and financing are at risk. Key person insurance helps fund the transition.

Operational continuity
Lender confidence
Transition time

Owner's income

A business owner generally doesn't have the same access to employment insurance as an employee. Disability insurance protects part of your personal income; who pays the premium changes the tax treatment.

Income replacement
Premium paid by you or the company
Tax treatment to confirm with your accountant

Capital on diagnosis

A cancer or stroke diagnosis can mean several months off work. Corporate critical illness pays a lump sum after diagnosis of a covered illness, under the contract, to help keep operations going.

Capital on diagnosis
Emergency fund
Tax treatment depends on structure
THE REALITY FOR SMALL BUSINESSES

The mistake Alexandre
sees most often.

Picking an insurance amount at random, or sticking to the required minimum, without accounting for personal expenses, business obligations, taxes or the succession plan. Alexandre starts instead from your financial statements, the company's organization chart and the tax impact of each type of insurance.
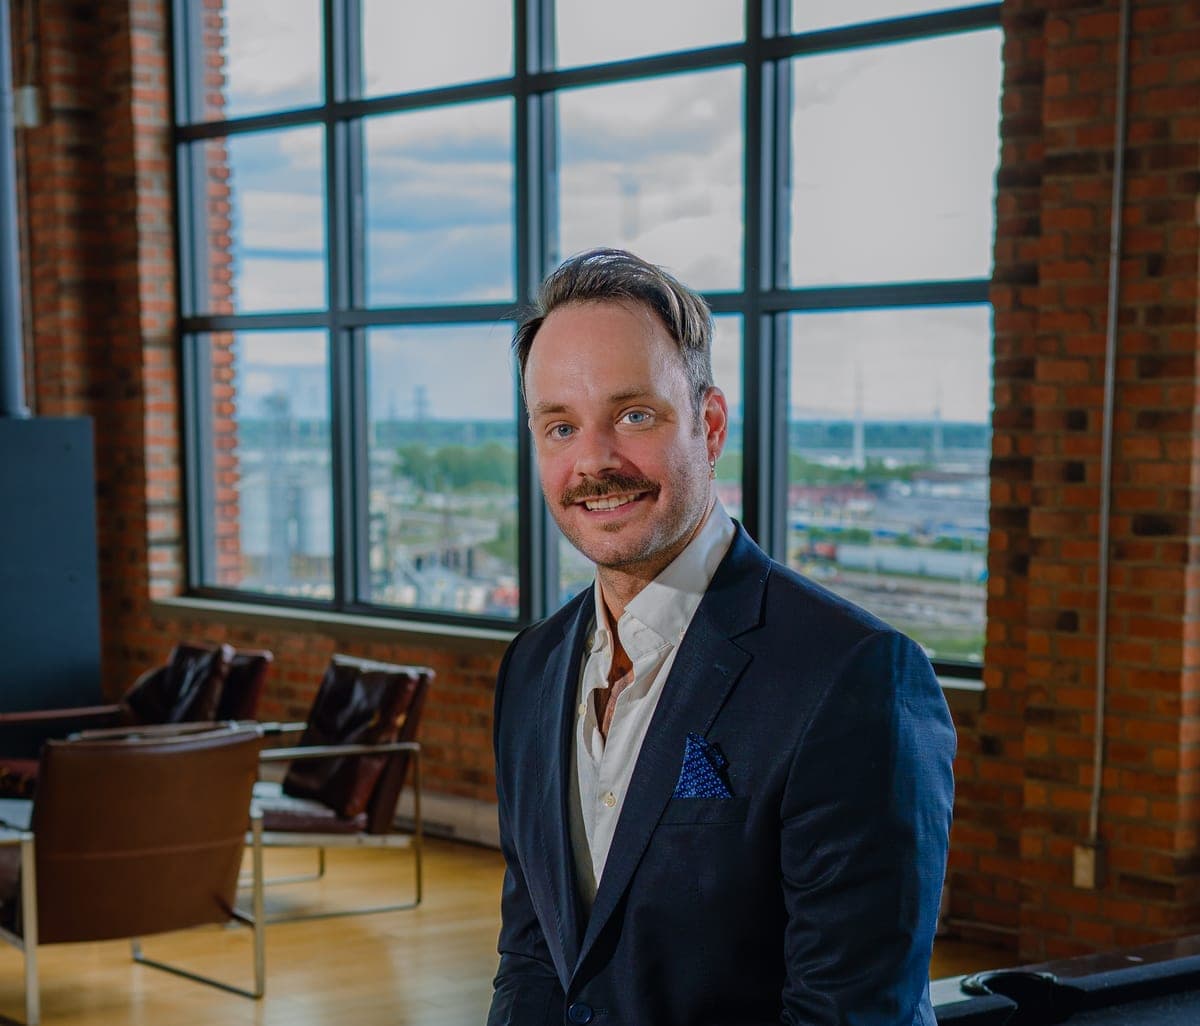
Alexandre Garneau, Financial Security Advisor in Montreal, who helps business owners with corporate insurance.
Business and corporate
AMF certificate no. 272275
CORPORATE SOLUTIONS

The 3 essential policies
for your business
PROTECTION LEVELS

What happens if you don't act?

No protection
Agreement only
Agreement + life insurance
RECOMMENDED
Share buyback fundedNoFrom existing cashYes
Capital paid on deathNoNoYes
Business continuity supportedNoUncertainYes
Possible tax advantage (CDA)NoNoYes
Protect my business
FAQ

Entrepreneurs' questions

Why take out life insurance through my company rather than personally?

When the company owns and is the beneficiary of the policy, the death benefit received, less the policy's adjusted cost basis, is generally added to the capital dividend account (CDA). The company can then pay that amount to its shareholders as a capital dividend, generally tax-free. The rules are specific: Alexandre works with your accountant to choose the right structure.

What happens to my business if I'm disabled for several months?

Unlike employees, business owners generally don't have automatic access to employment insurance sickness benefits. If your income comes from your company, a prolonged disability can put the business at risk. Disability insurance replaces part of your income, as set out in the contract. The tax treatment of the premium and the benefits depends on who pays the premium and on the structure; confirm it with your accountant.

What is a shareholder agreement and why is insurance necessary?

A shareholder agreement defines what happens to a shareholder's shares in case of death, disability or departure. Without adequate funding, surviving shareholders may be forced to accept heirs as partners or sell company assets to buy back the shares. Corporate life insurance can fund that buyback.

Are my disability premiums deductible in my company?

It depends on the structure. If you pay the premium on an individual policy yourself, it is generally not deductible, and the benefits are generally non-taxable. If the company pays the premium, other rules apply: the premium may be a taxable benefit for you, and the benefits may become taxable. The tax treatment depends on your situation; Alexandre compares the scenarios with you, and your accountant confirms them.

Do I need insurance if I already have significant cash in my company?

Maybe, but cash is usually needed to run operations. Using it to buy back shares leaves the business weakened at the worst time. Corporate life insurance is a predictable monthly cost for capital paid on death, as set out in the contract.

GOOGLE REVIEWS

What clients say

5.0 on Google · 10 reviews
“Thanks to Alexandre for the great advice on protecting myself and my business! I wasn't aware of all the insurance options available for my company.”
Ana Maria DanuletGoogle review · · Translated by Google
“Thank you for the advice regarding my business insurance.”
Marc-AndréGoogle review · · Translated by Google
“Excellent service from start to finish. Alexandre is very professional, attentive, and takes the time to explain the different options without putting any pressure on me. I felt well-advised and confident throughout the entire process. I highly recommend AG Financial Services.”
Anthony DussaultGoogle review · · Translated by Google

Reviews posted by clients on the Services Financiers AG Google listing, in French; the English text is Google's automatic translation. Every situation is different: a review does not predict the outcome of yours.

Free analysis

Talk with
Alexandre.

Fill out this form and get an analysis of your insurance needs, free and with no obligation. We aim to reply within 24 hours.

Free, no-obligation analysis
Personalized reply, usually within 24 hours
No sales pressure

Your information is confidential. It is used only to answer your request.