Services Financiers AG - Financial security advisor in Quebec.
CORPORATE INSURANCE

Disability:
deductible or not?

Who pays the disability insurance premium, you or your corporation? The answer changes how the premium and the benefit are taxed. For small business owners, shareholders and incorporated self-employed workers.

Talk to an advisor
HOW IT WORKS

How it works

There is no single "deductible policy": who pays the premium, and the type of plan, determine the tax treatment. Federal and Quebec rules differ.

Premium paid by the company

A corporation can generally deduct a premium it pays for coverage offered to an employee, including a shareholder who is also an employee. Eligibility depends on your structure: confirm it with your accountant.

Depends on your structure
Paid by the company
Accountant review

The tax trade-off

When the company pays, the tax shows up elsewhere: depending on the type of plan (group or individual), either the benefit becomes taxable or the premium becomes a taxable benefit for you.

Depends on the plan type
Federal and Quebec
Tax planning required

Combined approach possible

Some owners combine a personal policy with coverage paid by the company. The right mix depends on your compensation and your real needs.

Mixed approach possible
Based on your needs
Tailored for businesses

Protection for active owners

For owner-managers who actively work in their business and whose income depends on their ability to work.

Active owners
Shareholder managers
Incorporated self-employed
FREE ANALYSIS

You or your company: who should pay the premium?

Alexandre reviews your situation and calls you back with a personalized recommendation. Free, no obligation.

Review of your compensation structure
Coordination with your accountant
Comparative scenarios before deciding

Estimate your coverage

A few details are enough. Alexandre calls you back with a personalized, no-obligation estimate.

Free · No obligation · Confidential

The analysis is free. If you sign up, Alexandre is paid a commission by the insurer or product provider.

WHY THINK ABOUT IT?

You're an owner.
Your money is in
your company.

Many small business owners have no disability protection, because they think the business will pay. But if you're disabled, who runs it? And how do you pay yourself?

An unplanned personal disability also hits the business. Without planned income replacement, you have to dip into your savings or the company's.

The right setup, personal, corporate or both, depends on your compensation structure. Alexandre works it out with your accountant, not by guesswork.
60-85%
of net disposable income: the replacement range Alexandre generally aims for, based on your real needs and the insurer's cap
Source: Alexandre Garneau
2
possible payers of the premium, you or your company, and two different tax treatments of the premium and the benefit
Source: FCAC (canada.ca) and CRA
Analyze my case
Disability insurance for entrepreneurs - Services Financiers AG.
Who pays the premium?
You or your company
WHO IS IT FOR?

For which type of owner?

The owner-manager
Active business owner

The owner-manager

"Your income comes from your business - if you stop, it stops"

Who pays the premium: to decide
Covers the manager's salary
Maintains your lifestyle
The incorporated professional
Incorporated self-employed

The incorporated professional

"Your income goes through your company - so who pays the premium matters"

Review with your accountant
Complementary protection
Integrated into planning
The active shareholder
Active shareholder

The active shareholder

"You draw a salary from your own company"

Covers the shareholder's salary
Complements the agreement
Annual review recommended
WHY CHOOSE US

The Alexandre advantage

Choosing who pays the premium requires tax analysis. Alexandre coordinates with your accountant, who confirms the tax treatment for your situation.
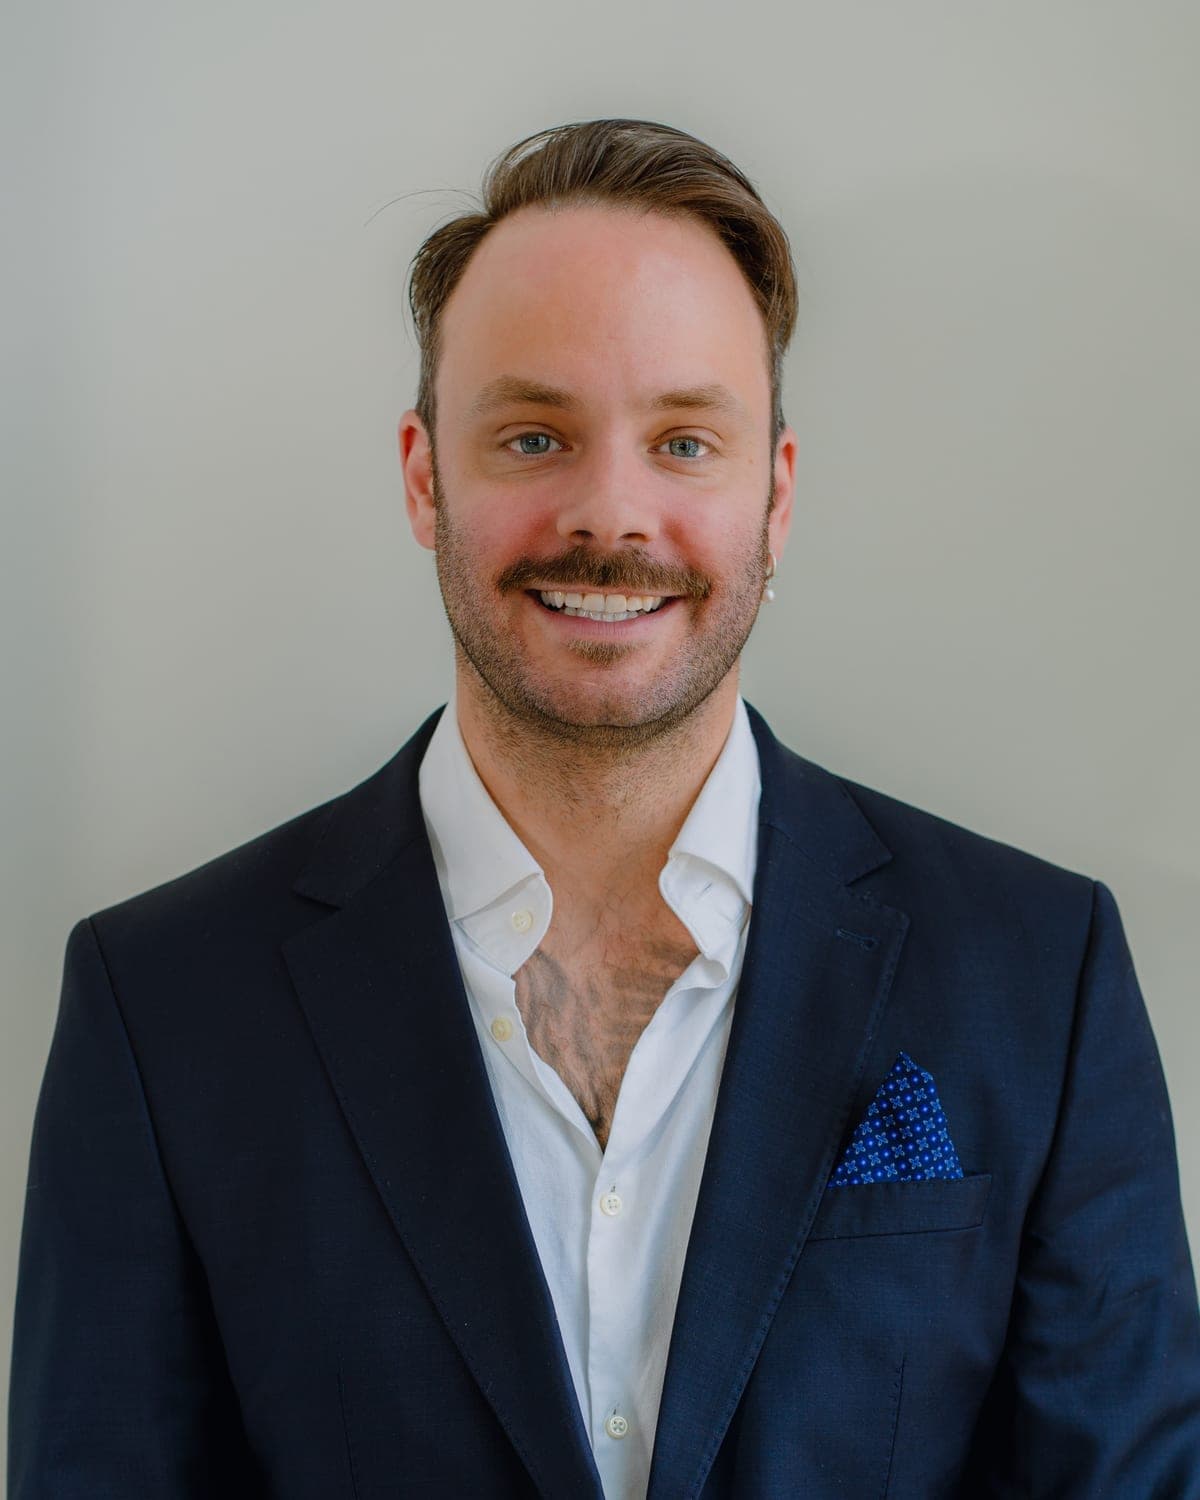
Scenarios compared
Premium paid by you or by the company: comparison based on your marginal rate and structure, confirmed by your accountant.
Accountant coordination
Alexandre works with your accountant, who confirms the tax treatment of the premium and the benefit.
Disability definition
Comparison of the definitions offered (own occupation, any occupation) and complementary clauses for your profession.
Mixed approach possible
Combination of a personal policy and coverage paid by the company, when it suits your situation.
Alexandre Garneau, financial security advisor, Services Financiers AG.
60-85%
Net income targeted
COMPARISON

Which approach suits you?

No protection
Premium paid by you
Premium paid by the company
BASED ON YOUR PROFILE
Premium paid byN/AYou personallyThe company
Premium deductible?N/AGenerally noGenerally, depending on structure
Benefit taxable?N/AGenerally noDepends on the plan type
Review by your accountantNoYesYes
Can combine with the other approachNoYesYes
Analyze my case

The tax treatment depends on your situation (employee or shareholder, group or individual plan, federal and Quebec rules). Confirm it with your accountant. Source for a policy you pay yourself: Financial Consumer Agency of Canada.

POINTS TO ANALYZE

The decisions
to make together

Every owner has a different structure. Alexandre analyzes the variables with your accountant.

Talk to Alexandre
You or your company: who pays?
Tax now or tax later

If you pay the entire premium of an individual disability policy yourself, the premium is generally not deductible and the benefits are generally tax-free (Financial Consumer Agency of Canada). If your company pays, other rules apply, federally and in Quebec. Your accountant confirms the tax treatment for your situation.

Your business structure
Corporation, partnership or sole proprietorship?

A business can generally deduct premiums it pays for its employees. An unincorporated self-employed person generally cannot deduct the premium of their own disability insurance: it is a personal expense. For a shareholder, the treatment depends on their status as an employee. Alexandre checks these points with your accountant.

The chosen disability definition
Own occupation or any occupation?

The disability definition is crucial. "Own occupation" means you are considered disabled if you can't perform your profession. "Any occupation" is more restrictive. The definitions offered vary by insurer and profession; Alexandre compares them with you.

Income to protect
Salary or dividends?

Insurers set the insurable amount based on eligible income, and the treatment of dividends varies by insurer. Alexandre analyzes your compensation structure to avoid a gap between the insured income and the income recognized at claim time.

PROCESS

How do you file a claim?

01
Disability declaration

Claim form completed with your attending physician as soon as the disability begins.

Waiting period per contract
02
Documentation

Medical history, specialist reports, proof of income.

Alexandre coordinates
03
Insurer assessment

The insurer reviews the file and confirms eligibility according to the policy definition.

Timeline set by the insurer
04
Monthly payout

Benefit paid each month. Its tax treatment depends on who paid the premium and the type of plan.

Monthly payout
COMPLETE YOUR STRATEGY

Related products

YOUR QUESTIONS

Frequently asked questions

Is my disability insurance deductible as a business expense?

Generally no, if it is a personal policy you pay yourself: it is a personal expense, even for a self-employed person. In return, if you pay the entire premium, the benefits are generally tax-free (Financial Consumer Agency of Canada). If your company or an employer pays, other rules apply. The tax treatment depends on your situation: confirm it with your accountant.

What happens if my company pays the premium?

The company can generally deduct a premium paid for an employee, including a shareholder-employee. According to the CRA, an individual plan premium paid by the employer is a taxable benefit for the employee; in a group wage-loss replacement plan, the premium is not a taxable benefit, but the benefits are taxable. Revenu Québec has its own rules. Your accountant confirms what applies to you.

Can I combine both approaches?

Yes, it is possible. A personal policy and coverage paid by the company can complement each other. Alexandre suggests a mix based on your needs, and your accountant confirms the tax treatment.

How do I calculate the amount to insure?

Alexandre starts with one question: if your income stopped tomorrow, how much would you need each month for the mortgage, personal expenses and business obligations? He generally aims for coverage that replaces 60% to 85% of net disposable income, based on your real needs and the insurer's cap.

What is the usual waiting period?

The waiting period is the time you must be disabled before benefits begin. Depending on the contract, it may be for example 30, 60, 90 or 120 days. The longer the period, the lower the premium. Alexandre helps you choose it based on your cash cushion.

If my disability ends, what happens to the policy?

The policy stays in force as long as you pay the premiums. If you return to work, benefits stop according to the policy terms. Some policies provide for a gradual return with partial benefits; Alexandre checks with you whether your policy includes this kind of clause.

What happens if my business closes?

A personal policy continues regardless of what happens to the business, as long as premiums are paid. A policy held by the company needs to be reassessed: transfer, keep or cancel, with tax consequences to confirm with your accountant. Alexandre plans this transition with you.

GOOGLE REVIEWS

What clients say

5.0 on Google · 10 reviews
“Thanks to Alexandre for the great advice on protecting myself and my business! I wasn't aware of all the insurance options available for my company.”
Ana Maria DanuletGoogle review · · Translated by Google
“Thank you for the advice regarding my business insurance.”
Marc-AndréGoogle review · · Translated by Google
“Alexandre explained the different types of personal insurance to me like no one else ever had. As a self-employed person, I didn't even know I could have income and disability insurance. I highly recommend him.”
Catherine BrasseurGoogle review · · Translated by Google

Reviews posted by clients on the Services Financiers AG Google listing, in French; the English text is Google's automatic translation. Every situation is different: a review does not predict the outcome of yours.

LET'S TALK

Protect your income,
with the right structure.

Alexandre analyzes your structure and compares the scenarios, with your accountant if you wish.

Reply within 48h
Coordination with your accountant
AMF certificate no. 272275

An email or a phone number is enough.

Confidential. Used only to answer your request.