Services Financiers AG - Financial security advisor in Quebec.
CORPORATE INSURANCE

Corporate life
insurance.

Protect your business against the loss of a key partner. Fund your shareholder agreement, plan succession and prepare the transfer of your business.

Talk to an advisor
COVERAGE

What this strategy includes

Corporate life insurance is as much a business planning tool as a protection mechanism - it helps protect the continuity of your business.

Shareholder agreement

Funding the share buyback on the death of a partner, under the terms of the agreement - so inactive heirs don't become shareholders.

Buyback set by the agreement
Planned continuity
Liquid funding on death

Key person protection

Capital paid to the business on the death of a leader or essential employee - to keep operations going during replacement.

Capital paid to the business
Operations maintained
Replacement funded

Tax treatment of premiums

As a rule, life insurance premiums are not deductible for the company. A partial deduction is possible in specific cases, for example when a lender requires the policy as security for a business loan.

Accountant consultation required
Premium generally not deductible
Tailored structure

Business succession planning

Transfer of the business's value to heirs in an organized way - with liquidity available to meet tax obligations on death.

Planned succession
Liquidity on death
Fewer conflicts
FREE ANALYSIS

Your corporate strategy, step by step.

Alexandre reviews your situation and calls you back with a personalized recommendation. Free, no obligation.

Coordination with your accountant
Analysis of your current agreement
No obligation to sign up

Estimate your coverage

A few details are enough. Alexandre calls you back with a personalized, no-obligation estimate.

Free · No obligation · Confidential

The analysis is free. If you sign up, Alexandre is paid a commission by the insurer or product provider.

WHY THIS STRATEGY?

Your business is
your greatest asset.
Protect it.

Many businesses don't have the cash needed to absorb the shock of a partner's death. Corporate life insurance can create that liquidity when you need it.

Without a plan, a partner's death can force a rushed sale or new debt to buy back their shares. A clear structure avoids that crisis.

The amount and structure depend on your shareholder agreement, your revenue and your succession plan. Alexandre works with your accountant and notary to align it properly.

Protect my business
Corporate life insurance for businesses - Services Financiers AG.
AMF certificate no. 272275
Financial Security Advisor
WHO IS IT FOR?

For which type of business?

The company with partners
Two or more partners

The company with partners

"What happens if your partner dies tomorrow?"

Shareholder agreement funded
Share buyback by the company
Shares bought back under the agreement
The business with a key person
Essential employee

The business with a key person

"Your revenue depends on one specific person"

Capital to bridge the gap
Recruitment funded
Revenue protected
The family business
Family transfer

The family business

"You want to pass on the business, not liquidate it"

Liquidity for taxes on death
Buyback of inactive heirs' shares
Operations maintained
WHY CHOOSE US

The Alexandre advantage

Corporate life insurance requires coordination between your advisor, your accountant and your notary. Alexandre orchestrates that collaboration so every piece is in place.
SMBs and corporate
Support for Quebec businesses with succession, transfer and continuity issues.
Professional coordination
Alexandre works with your accountant and your notary - so the policy fits into your structure.
iA Financial Group and MRa
Access to iA Financial Group's corporate insurance products and MRa products.
Annual review
Updating coverage based on the current value of the business - your policy evolves with your company.
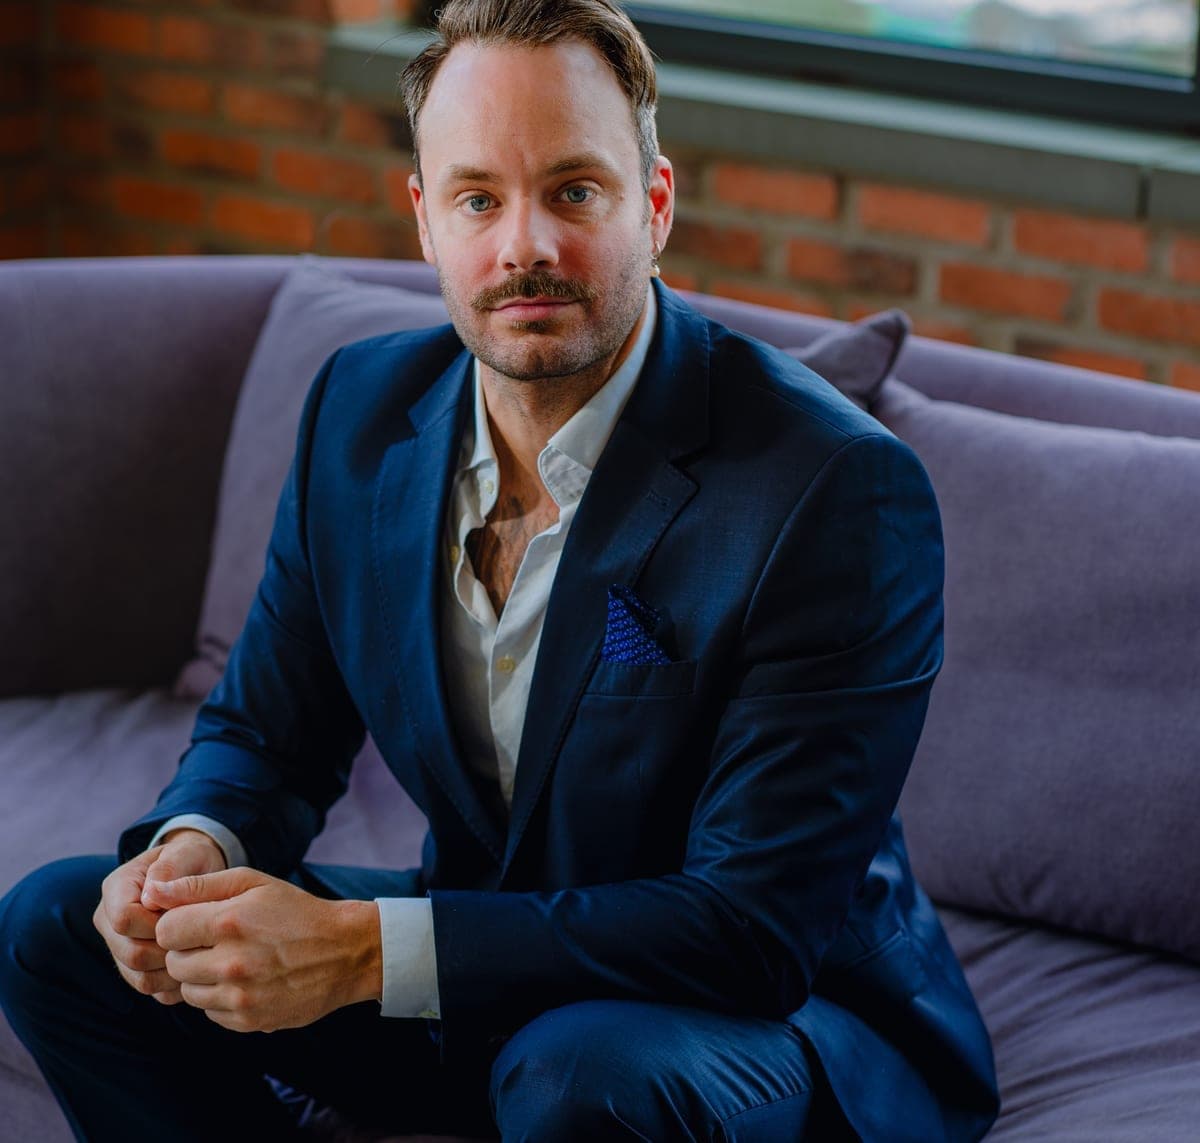
Alexandre Garneau, Financial Security Advisor, Services Financiers AG.
SMB
Support in Quebec
COMPARISON

With or without an insurance strategy

No planning
Agreement only
Agreement + life insurance
RECOMMENDED
Liquidity on deathNoneLimitedDeath benefit set by contract
Business continuityNoPartialYes
Protection of surviving partnersNoNoYes
Possible CDA creditNoNoDepends on structure
Organized successionNoPartialYes
CostNoneLegal feesLegal fees and premiums
Choose this strategy
STRUCTURE FACTORS

How to structure
your strategy?

Several variables influence the right structure. Alexandre guides every decision with your team of professionals.

Analyze my business
Number and profile of partners
Ownership structure determines the strategy

A cross policy between partners, a policy held by the company or a hybrid structure - each configuration has different tax implications. Alexandre analyzes with your accountant to choose a suitable structure.

Value of the business
The capital must match the real value

The policy amount must reflect the fair market value of the shares to be bought back. Alexandre helps you set a starting value and plan for an annual revision mechanism.

Age and health of partners
Determines the cost of each policy

Each partner has their own risk profile. The premium of each policy depends on the age, health and amount to be covered for that specific partner.

Goal: term or permanent?
Depending on the agreement's horizon

Term coverage may be enough if the shareholder agreement has a defined term. Permanent coverage may be preferable for a long-lived business - some permanent policies also build a cash value the company can use.

PROCESS

How does it work on death?

An organized process that helps protect your business's continuity.

01
Notification

The company notifies the insurer of the covered partner's death.

As soon as possible
02
Documentation

Death certificate, shareholder agreement, policy statement, board resolutions.

Alexandre coordinates
03
Payout

Capital paid to the company, generally tax-free. The portion above the policy's adjusted cost basis can be credited to the CDA.

Generally tax-free
04
Buyback

The company buys back the heirs' shares according to the terms of the agreement.

Under the agreement
COMPLETE YOUR STRATEGY

Related products

YOUR QUESTIONS

Frequently asked questions

What is a shareholder agreement funded by life insurance?

It's an agreement between partners stating that, on the death of one of them, the survivors may (or must) buy back their shares at a predefined price. Life insurance funds that buyback - the company or the surviving partners receive the necessary capital exactly when they need it.

What's the difference between a cross policy and a company-owned policy?

In a cross structure, each partner holds a policy on the others' lives. In a corporate structure, the company is owner and beneficiary of the policy. The tax implications differ by structure. Alexandre analyzes with your accountant to choose the right approach.

Are corporate life insurance premiums deductible?

As a rule, no. A partial deduction may apply in specific cases, for example when a lender requires the policy as security for a business loan. The tax value mainly lies elsewhere: the death benefit received by a private company is generally tax-free, and the portion above the policy's adjusted cost basis can be credited to the Capital Dividend Account (CDA), then paid to shareholders as tax-free capital dividends. Confirm with your accountant based on your structure.

What is the Capital Dividend Account (CDA)?

The Capital Dividend Account (CDA) is a tax account of a private company that grows when it receives certain non-taxable amounts, including a life insurance death benefit minus the policy's adjusted cost basis. The company can then pay these amounts to shareholders as tax-free capital dividends, provided the required election is filed. It's a significant tax advantage of company-owned life insurance, to confirm with your accountant.

How do you assess the amount to insure for a key person?

The amount depends on the key employee's contribution to the company's revenue, the estimated cost of replacing them (recruitment, training, lost clients) and the time needed to stabilize operations. Alexandre uses a structured formula with your accountant to set a defensible amount.

Do you need a shareholder agreement to take out corporate life insurance?

No - a key person policy can exist independently of an agreement. But if the goal is to fund a share buyback, an up-to-date agreement is essential for the strategy to work. Alexandre works with your notary or lawyer to ensure both documents are consistent.

What happens if a partner leaves the business without dying?

The policy stays in force, but its purpose changes. It can be transferred, bought out by the departing partner, or repurposed for a new corporate goal. A policy transfer can have tax consequences, to confirm with your accountant. Alexandre reviews the structure at every ownership change.

How long does setting up a corporate policy take?

It varies with the amount requested and the medical exams required, but expect a few weeks generally. Alexandre coordinates the process with your accountant to avoid delays.

GOOGLE REVIEWS

What clients say

5.0 on Google · 10 reviews
“Thanks to Alexandre for the great advice on protecting myself and my business! I wasn't aware of all the insurance options available for my company.”
Ana Maria DanuletGoogle review · · Translated by Google
“Thank you for the advice regarding my business insurance.”
Marc-AndréGoogle review · · Translated by Google
“Excellent service from start to finish. Alexandre is very professional, attentive, and takes the time to explain the different options without putting any pressure on me. I felt well-advised and confident throughout the entire process. I highly recommend AG Financial Services.”
Anthony DussaultGoogle review · · Translated by Google

Reviews posted by clients on the Services Financiers AG Google listing, in French; the English text is Google's automatic translation. Every situation is different: a review does not predict the outcome of yours.

LET'S TALK

Protect your business
right now.

Alexandre analyzes your ownership and your current agreement - and proposes a tailored corporate insurance strategy.

Reply within 48h
Coordination with your accountant
AMF certificate no. 272275

An email or a phone number is enough.

Confidential. Used only to answer your request.