Services Financiers AG - Financial security advisor in Quebec.
CLIENT PROFILE

Are you a
self-employed worker?

Consultant, freelancer, independent professional - you built your freedom. But if you stop working, your income stops too. Alexandre helps you protect what you've built.

Independent consultant self-employed worker - Services Financiers AG insurance.
ConsultantFreelancerIndependent
No group plan
Variable income
No automatic employment insurance
Solely responsible for your care
FREE ANALYSIS

If you stop working
tomorrow, what happens?

Alexandre reviews your situation and calls you back with a personalized recommendation. Free, no obligation.

Analysis of your income and risks
Comparison of disability, critical illness, life
A proposal suited to your type of activity

Estimate your coverage

A few details are enough. Alexandre calls you back with a personalized, no-obligation estimate.

Free · No obligation · Confidential

The analysis is free. If you sign up, Alexandre is paid a commission by the insurer or product provider.

YOUR VULNERABILITIES

What no one covers
in your place

Unlike an employee, you have no collective safety net. Each protection must be built individually.

Income replacement

This is often your biggest risk. No employer, no union, no group insurance - if you become disabled, your income stops. An individual disability policy replaces part of it, as set out in the contract.

Monthly income protected
Waiting period you choose
Occupation definition per the contract

Lump sum on diagnosis

Cancer, stroke, heart attack - a serious diagnosis can mean several months of full stoppage. Critical illness insurance pays you a lump sum, under the terms of the contract, to get through that period.

Paid on diagnosis
Generally non-taxable
List of illnesses per the contract

Life protection for your family

Even without a mortgage, your loved ones may depend on your income. Affordable term life insurance protects them if you pass away.

Death benefit generally tax-free
Fixed premium for the term
Family as direct beneficiary

Mortgage protection

If you own your home and your income is variable, a disability or death can leave your mortgage unprotected. An individual policy with fixed coverage can fill that gap.

Fixed coverage
Independent of the bank
Portable between institutions
THE REALITY FOR THE SELF-EMPLOYED

You're more exposed
than you think.

The question Alexandre asks: if your income stopped tomorrow because of an accident or illness, how much would you need each month for the mortgage, personal expenses and business obligations? He generally aims for coverage that replaces 60% to 85% of net disposable income, based on your real needs and the cap set by the insurer.
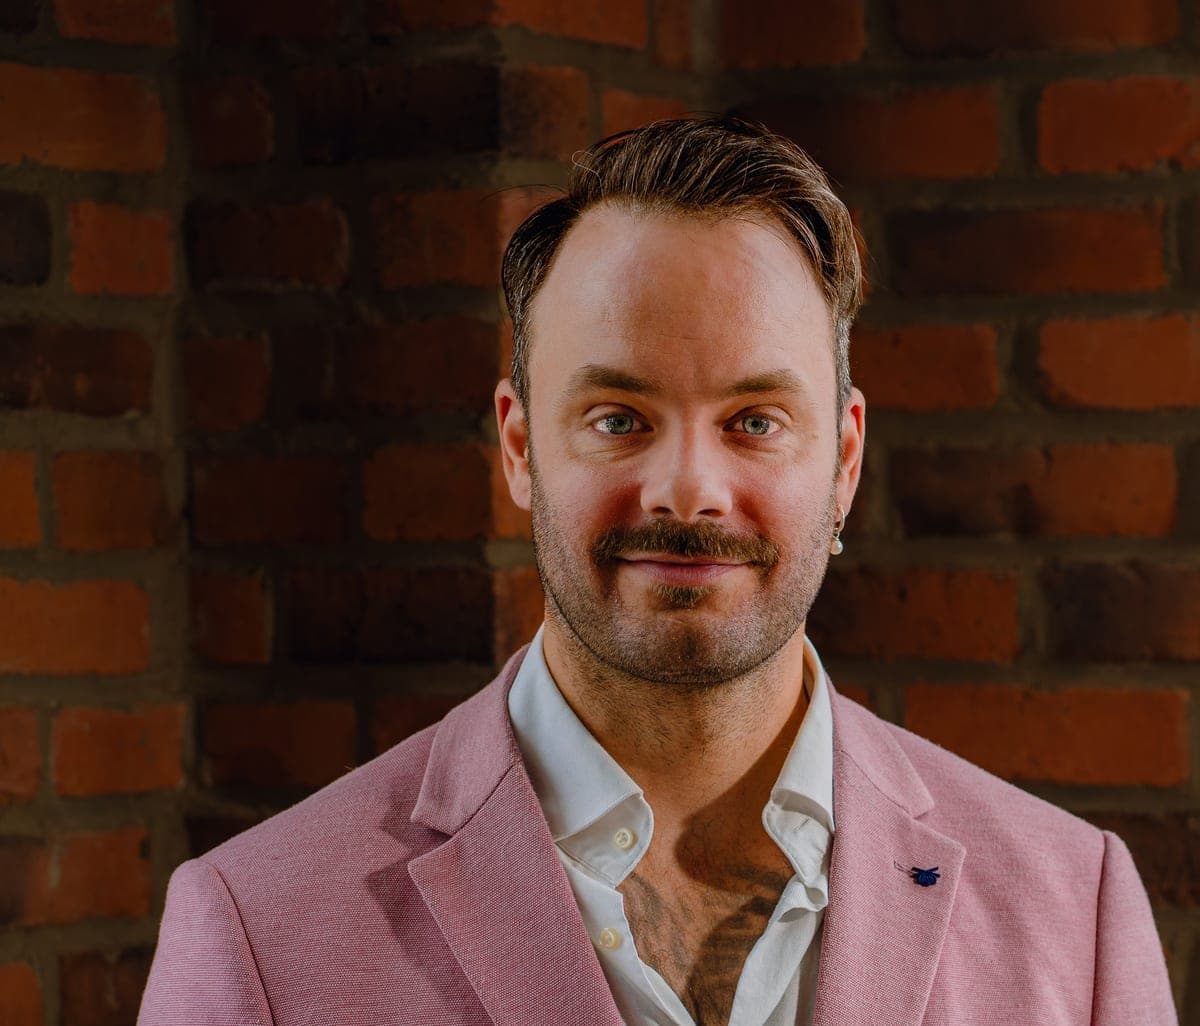
Alexandre Garneau, Financial Security Advisor in Montreal, who helps self-employed workers with disability, critical illness and life insurance.
Self-employed workers
AMF certificate no. 272275
YOUR SOLUTIONS

The 3 policies to consider
first

Before choosing your life insurance, read our article 7 things to know about life insurance when you're self-employed.

PROTECTION LEVELS

Choose your level of coverage

No coverage
Disability only
Combined protection
RECOMMENDED
Income maintained if disabledNoYesYes
Lump sum if critical illnessNoNoYes
Family protected if deathNoNoYes
Mortgage coveredNoNoYes
Suited to variable incomeNoPartiallyYes
Get this protection
FAQ

Self-employed workers' questions

Am I entitled to employment insurance if I become disabled as a self-employed worker?

Not automatically. Self-employed workers don't contribute to employment insurance by default. They can voluntarily register for EI special benefits for the self-employed, which include sickness benefits for a limited period. The RQAP covers maternity, paternity and parental leave, not illness. For a prolonged disability, no public plan automatically replaces your income: individual disability insurance is often the main protection.

How does disability insurance work for a variable income?

Coverage is generally based on your net income over recent years, according to the insurer's rules. The premium is adjusted accordingly. Some policies let you increase coverage without new medical evidence if your income rises, as set out in the contract. Alexandre generally aims for 60% to 85% of net disposable income and tailors the amount and clauses to your type of income.

What is the occupation definition in a disability policy?

The occupation definition (or own-occupation definition) is one of the most important clauses in a disability policy. It provides that you're considered disabled if you can no longer perform YOUR occupation - not just any job. With an "any occupation" definition, the insurer may, under the contract, stop benefits if you can do other work suited to your education or experience.

How much does disability insurance cost for a self-employed worker?

It depends on your age, health, income, occupation, waiting period and the definition clause. The gap between two profiles can be large: only a quote based on your file gives a reliable price. Alexandre prepares a free estimate for you.

Is my disability insurance premium tax-deductible?

If you pay the premium on an individual policy yourself, it is generally not deductible, and the benefits received in case of disability are generally non-taxable. If your corporation pays the premium (incorporated self-employed), other rules apply: the premium may be a taxable benefit and the benefits may become taxable, depending on the structure. The tax treatment depends on your situation; confirm it with your accountant.

GOOGLE REVIEWS

What clients say

5.0 on Google · 10 reviews
“Alexandre explained the different types of personal insurance to me like no one else ever had. As a self-employed person, I didn't even know I could have income and disability insurance. I highly recommend him.”
Catherine BrasseurGoogle review · · Translated by Google
“Excellent service from start to finish. Alexandre is very professional, attentive, and takes the time to explain the different options without putting any pressure on me. I felt well-advised and confident throughout the entire process. I highly recommend AG Financial Services.”
Anthony DussaultGoogle review · · Translated by Google
“Alexandre helped me with my financial situation. He showed me the steps to take and how to structure my plan effectively. I highly recommend him!”
Jeremi DescoteauxGoogle review · · Translated by Google

Reviews posted by clients on the Services Financiers AG Google listing, in French; the English text is Google's automatic translation. Every situation is different: a review does not predict the outcome of yours.

Free analysis

Talk with
Alexandre.

Fill out this form and get an analysis of your insurance needs, free and with no obligation. We aim to reply within 24 hours.

Free, no-obligation analysis
Personalized reply, usually within 24 hours
No sales pressure

Your information is confidential. It is used only to answer your request.