Services Financiers AG - Financial security advisor in Quebec.
TAX-FREE SAVINGS

Your TFSA
in segregated funds.

Grow your savings tax-free and withdraw them whenever you want. In segregated funds, your TFSA also lets you, in Quebec, name a beneficiary directly in the contract, without going through your will.

Alexandre Garneau, Financial Security Advisor in Montreal, who helps clients with their TFSA strategy.
COVERAGE

What the TFSA gives you

A flexible plan, with no deadline to use it, that adapts to your projects rather than the other way around.

Tax-free withdrawals

You take out the amount you want, when you want. Withdrawals aren't added to your income and, as a rule, aren't taxed.

No tax on withdrawal
Nothing to report
Access to your money

Tax-sheltered growth

As long as the money stays in the plan, growth is not taxed. Nothing to report each year.

No annual tax
Sheltered growth
Any project horizon

A beneficiary in the contract

In Quebec, only a TFSA that is an insurance contract lets you name a beneficiary directly. In segregated funds, it also provides a 75% to 100% guarantee at maturity or on death, depending on the contract.

Beneficiary named in the contract
Possible transfer outside the estate
Protection per the contract

Room carries forward indefinitely

Room you don't use carries forward indefinitely. A withdrawal is added back to your room the following year.

Indefinite carry-forward
Withdrawal restored next year
Room shown on the CRA portal
ON DEATH

In Quebec, who receives your TFSA when you die?

The short answer

In Quebec, you can name a beneficiary directly in your TFSA contract only if it is an insurance product, such as a segregated-fund TFSA. A deposit or investment TFSA at the bank is passed on according to your will, or according to the law if you don't have one.

Segregated-fund TFSA
At AG
Bank TFSA
Deposit, GIC, mutual funds
Beneficiary named in the contractYesNot in Quebec: through your will
Payout on deathDirectly to the beneficiary, outside the estateGoes through the estate
Wait for your loved onesGenerally shorter (no estate settlement)Waits for the estate to be settled
Capital guarantee75% to 100% at maturity or on death, depending on the contract (withdrawals can reduce it)None for mutual funds; capital guaranteed for a GIC, with a return set in advance
Protection from creditorsPossible under certain conditions, notably depending on the named beneficiaryGenerally not
FeesHigher: the guarantees have a costGenerally lower
Talk it over with Alexandre

Income earned in the TFSA after death may be taxable to the beneficiary; the value at death is not. A will remains essential for the rest of your assets. A segregated fund is not an ordinary investment account: its value can go down and no rate of return is guaranteed.

CONTRIBUTION ROOM

Your TFSA contribution room

The short answer

Your room is the sum of the annual limits since you turned 18 (or since 2009), minus your contributions, plus your withdrawals from previous years. If you were 18 in 2009, have lived in Canada since and have never contributed, your room is $109,000 in 2026.

$7,000
TFSA contribution limit for 2026
Source: Canada.ca
$109,000
Maximum cumulative room in 2026
Source: Canada.ca
1%
per month of tax on an over-contribution
Source: Canada.ca
How to find your exact room

In CRA My Account, under TFSA. Note: contributions made in the current year don't always show up there right away.
Plan my contribution
Alexandre Garneau meeting a client in Montreal to plan their TFSA.
AMF certificate no. 272275
Financial Security Advisor
BY THE NUMBERS

The long-term effect of a TFSA

Take an eligible person who doesn't contribute for three years. Their room doesn't disappear: it accumulates.

The annual limit is $7,000 for 2024, for 2025 and for 2026. After three years without contributing, they have $21,000 of room.

Fictional example
Room accumulated after three years without contributing$21,000
$0$7,000$14,000$21,000$7,000After 2024$14,000After 2025$21,000After 2026
2024 limit: $7,000
2025 limit: $7,000
2026 limit: $7,000
$7,000TFSA annual limit for 2026. The same amount applied for 2025 and for 2024
$21,000A simple addition of the three annual limits, for an eligible person who contributed in none of those years
1%per month of tax on the highest excess amount in the month, for as long as it stays in the plan

A withdrawal comes back to you, but only the following year

This is a common TFSA trap. The amount you take out is not added back to your room right away.

The amount withdrawn is added to your room at the beginning of the following year
Recontributing that amount in the same year can create an over-contribution
The excess is taxed 1% per month, on the highest amount in the month
Unlike the RRSP, the TFSA offers no over-contribution cushion

Fictional example, for illustration only. No rate of return is shown or implied. Your actual contribution room appears in CRA My Account. Source: Canada Revenue Agency.

FREE ANALYSIS

Your TFSA strategy,
without leaving home.

Alexandre reviews your situation and calls you back with a personalized recommendation. Free, no obligation.

No endless form
A quick reply
No obligation to sign up

Plan your TFSA

A few details are enough. Alexandre calls you back with a personalized, no-obligation estimate.

Free · No obligation · Confidential

The analysis is free. If you sign up, Alexandre is paid a commission by the insurer or product provider.

WHO IS IT FOR?

Who is it useful for?

The self-employed
Self-employed

The self-employed

"Your income varies and you want to keep money within reach"

Emergency fund, tax-free on withdrawal
TFSA in low-income years, RRSP in strong years
Beneficiary named in the contract
The employee with a project
Employee

The employee with a project

"You're saving for something specific"

Tax-free withdrawal when you need it
Automatic contributions possible
Room withdrawn comes back next year
The couple and the retiree
Couple and family

The couple and the retiree

"You want to protect your benefits"

Doesn't affect income-tested federal benefits
Natural complement to the RRSP
Named beneficiary on the contract
FHSA

Buying your first home?

The FHSA combines the RRSP deduction with the TFSA's tax-free withdrawal, up to $8,000 per year and $40,000 over your lifetime. Everything is explained in our FHSA article.

WHY CHOOSE US

The Alexandre advantage

No bureaucracy, no call center. Alexandre takes the time to understand your situation and offers solutions that truly fit you.

A clear read on your room
Alexandre confirms your contribution room with you before setting the amount that suits you.
Independent of your bank
Not a bank advisor. The recommendation starts from your situation and your profile.
Annual follow-up at no cost
Your file is reviewed every year to adapt to your projects and your goals.

Before any recommendation, Alexandre establishes your investor profile. See how he works
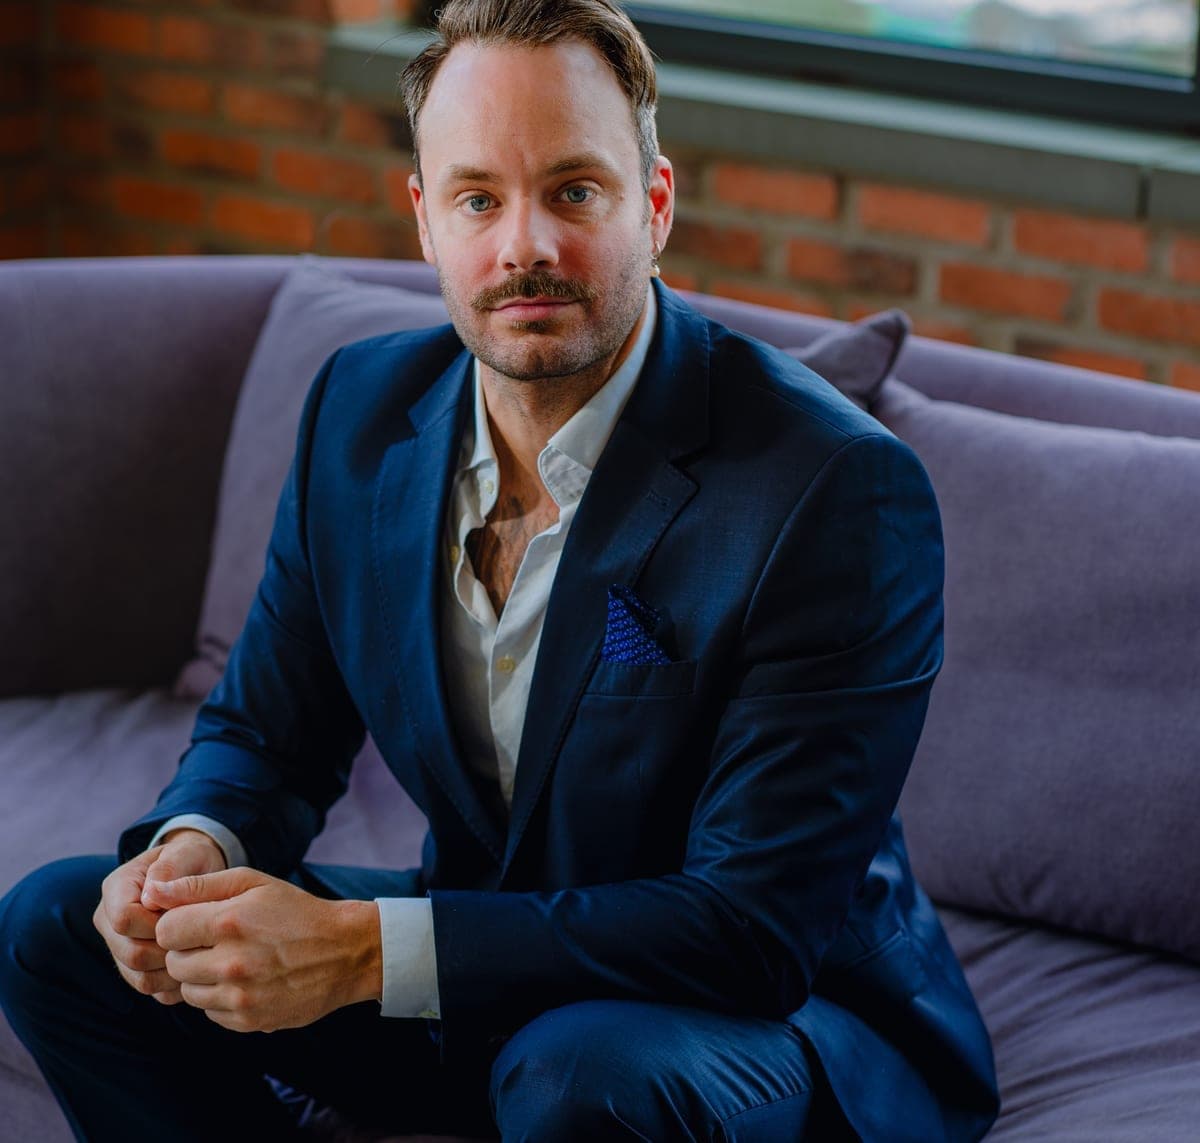
Alexandre Garneau, Financial Security Advisor, Services Financiers AG.
GO FURTHER

Complete your plan

YOUR QUESTIONS

Frequently asked questions

Can I name a beneficiary for my TFSA in Quebec?

Directly in the contract, only if your TFSA is an insurance product, such as a segregated-fund TFSA. For a bank TFSA, the transfer follows your will. Can your spouse take over the account? That depends on the contract: Alexandre checks with the insurer.

How much TFSA contribution room do I have?

Your room is the sum of the annual limits since you turned 18 (or since 2009), minus your contributions, plus your withdrawals from previous years. If you were 18 in 2009, have lived in Canada since and have never contributed, your room is $109,000 in 2026. Your exact room appears in CRA My Account, under TFSA; contributions made in the current year don't always show up there right away.

Can I withdraw from my TFSA whenever I want?

Yes. You take out the amount you want, at the time you want, with no tax and no need to justify the use. The amount withdrawn is added back to your contribution room, but only the following year. Recontributing in the same year can create an over-contribution.

What happens if I contribute too much?

A tax of 1% per month applies to the highest excess amount in the month, for as long as it stays in the plan. Unlike the RRSP, the TFSA offers no tolerance cushion. Always check your room with the CRA before contributing, especially after a withdrawal.

Does the TFSA affect my benefits?

Not federal income-tested benefits. According to the CRA, neither income earned in a TFSA nor withdrawals from it affect eligibility for federal income-tested benefits and credits, such as Old Age Security or the Canada child benefit. That's an important difference from the RRSP, whose withdrawals are added to your taxable income and can reduce those benefits.

TFSA or RRSP: which should I choose?

Generally, the RRSP is more advantageous if your tax rate today is higher than the one you'll have in retirement, and the TFSA if your income is modest or you'll need the money before retirement. The two often work well together.

See the three typical situations on the RRSP page
LET'S TALK

Grow your savings
tax-sheltered.

A few minutes is enough. Alexandre calls you back with a personalized recommendation, no obligation.

Quick reply
No obligation
AMF certificate no. 272275

An email or a phone number is enough.

Confidential. Used only to answer your request.