Services Financiers AG - Financial security advisor in Quebec.
CORPORATE INSURANCE

Corporate critical
illness.

A lump sum paid to your business if a leader is diagnosed with an illness covered by the contract - to fund the continuity of operations without dipping into your cash flow.

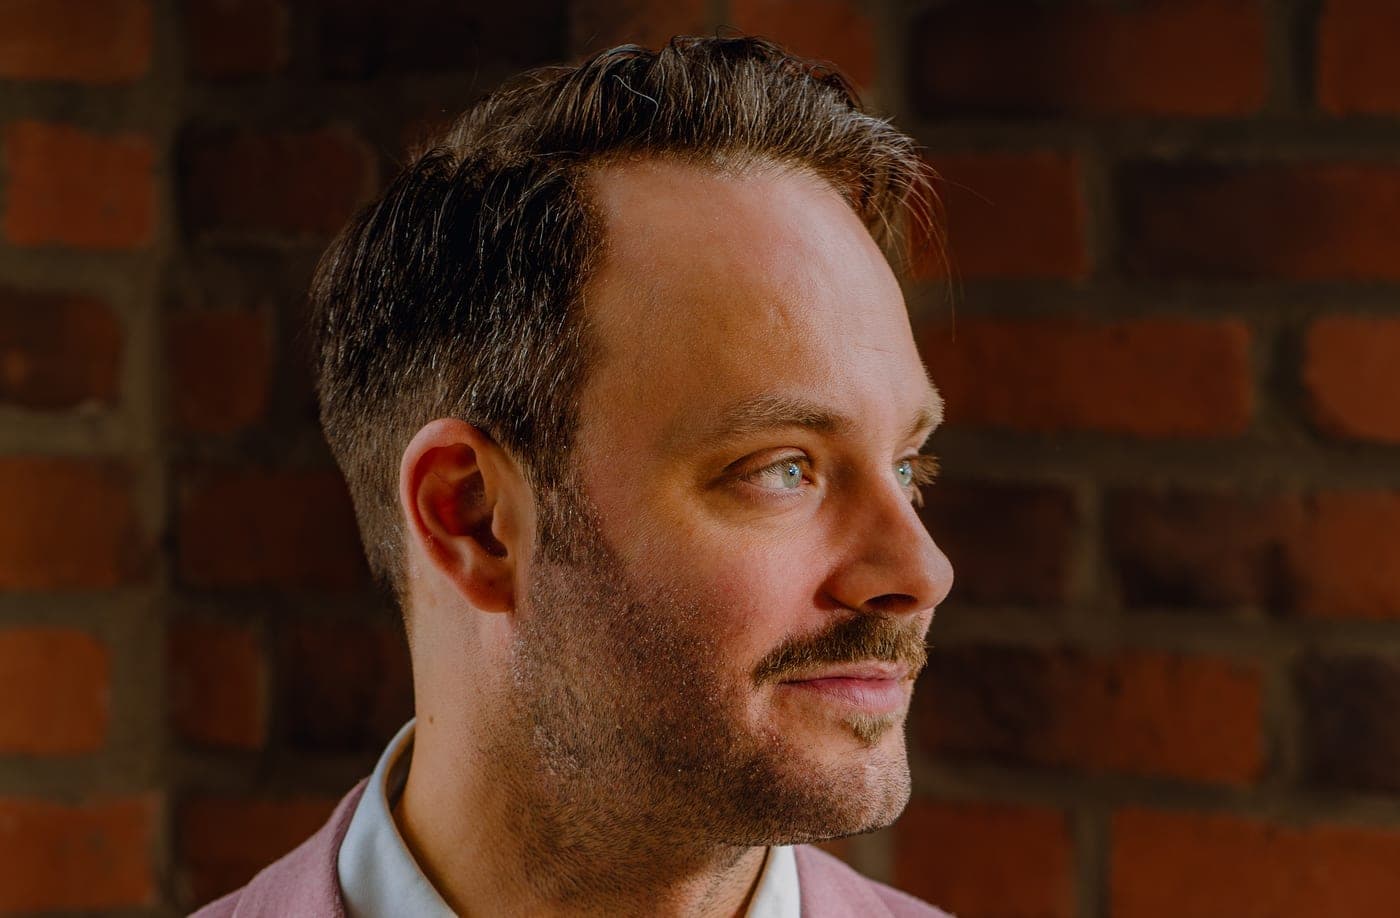
Alexandre Garneau, Financial Security Advisor in Montreal, helping businesses with corporate critical illness insurance.
COVERAGE

What this protection covers

Corporate critical illness insurance protects your company's financial health if a leader, partner or key employee is diagnosed with a covered illness.

Capital on diagnosis

Lump-sum payment to the company once the claim is accepted, after the survival period set out in the contract (often 30 days).

Single payout
Generally non-taxable*
Free use

Continuity of operations

Funds available to hire a temporary replacement, maintain operations and honor the business's commitments.

HR funding
Contracts maintained
Financial bridge

Emergency succession plan

Transition capital if a partner is out of action for an extended period - without being forced to sell company assets.

Transition time
Organized succession
Assets preserved

Complementary personal protection

The policy can be held personally or by the company, depending on your tax situation - Alexandre analyzes the right structure with your accountant.

Tailored structure
Tax treatment to confirm
Accountant coordination

* Tax treatment depends on the policy structure. Consult your accountant. Alexandre can coordinate.

FREE ANALYSIS

Is your business protected against the unpredictable?

Alexandre reviews your situation and calls you back with a personalized recommendation. Free, no obligation.

Analysis of your business's human vulnerabilities
Coordination with your accountant
No obligation to sign up

Estimate your coverage

A few details are enough. Alexandre calls you back with a personalized, no-obligation estimate.

Free · No obligation · Confidential

The analysis is free. If you sign up, Alexandre is paid a commission by the insurer or product provider.

WHY THIS PROTECTION?

A diagnosis shouldn't
put your business at risk.

Illness gives no warning. If your key leader receives a diagnosis tomorrow morning, your business must be able to absorb the shock without dipping into its operating cash.

The gap shows up fast. Recruiting, training, lost clients - the cost of replacing a key leader piles up within the first weeks.

The amount to insure depends on the person's role, not just their salary. Alexandre assesses the real value they bring to the business.

Protect my business
Corporate critical illness - business protection - Services Financiers AG.
AMF certificate no. 272275
Financial Security Advisor
WHO IS IT FOR?

For which type of business?

The company with partners
Two or more partners

The company with partners

"A diagnosis could paralyze decisions"

Capital available for the operational bridge
Funding for a temporary replacement
No decisions forced under pressure
The incorporated professional
Incorporated professional

The incorporated professional

"Your income rests on your ability to work"

Protection of the company's revenue
Professional obligations maintained
Time to focus on treatment
The business with a key person
Business with key employee

The business with a key person

"One person carries a large share of your revenue"

Funding for emergency recruitment
Client relationships maintained
Time to stabilize operations
WHY CHOOSE US

The Alexandre advantage

Alexandre knows the specific challenges of Quebec businesses - and he coordinates with your accountant so the critical illness strategy fits into your overall planning.
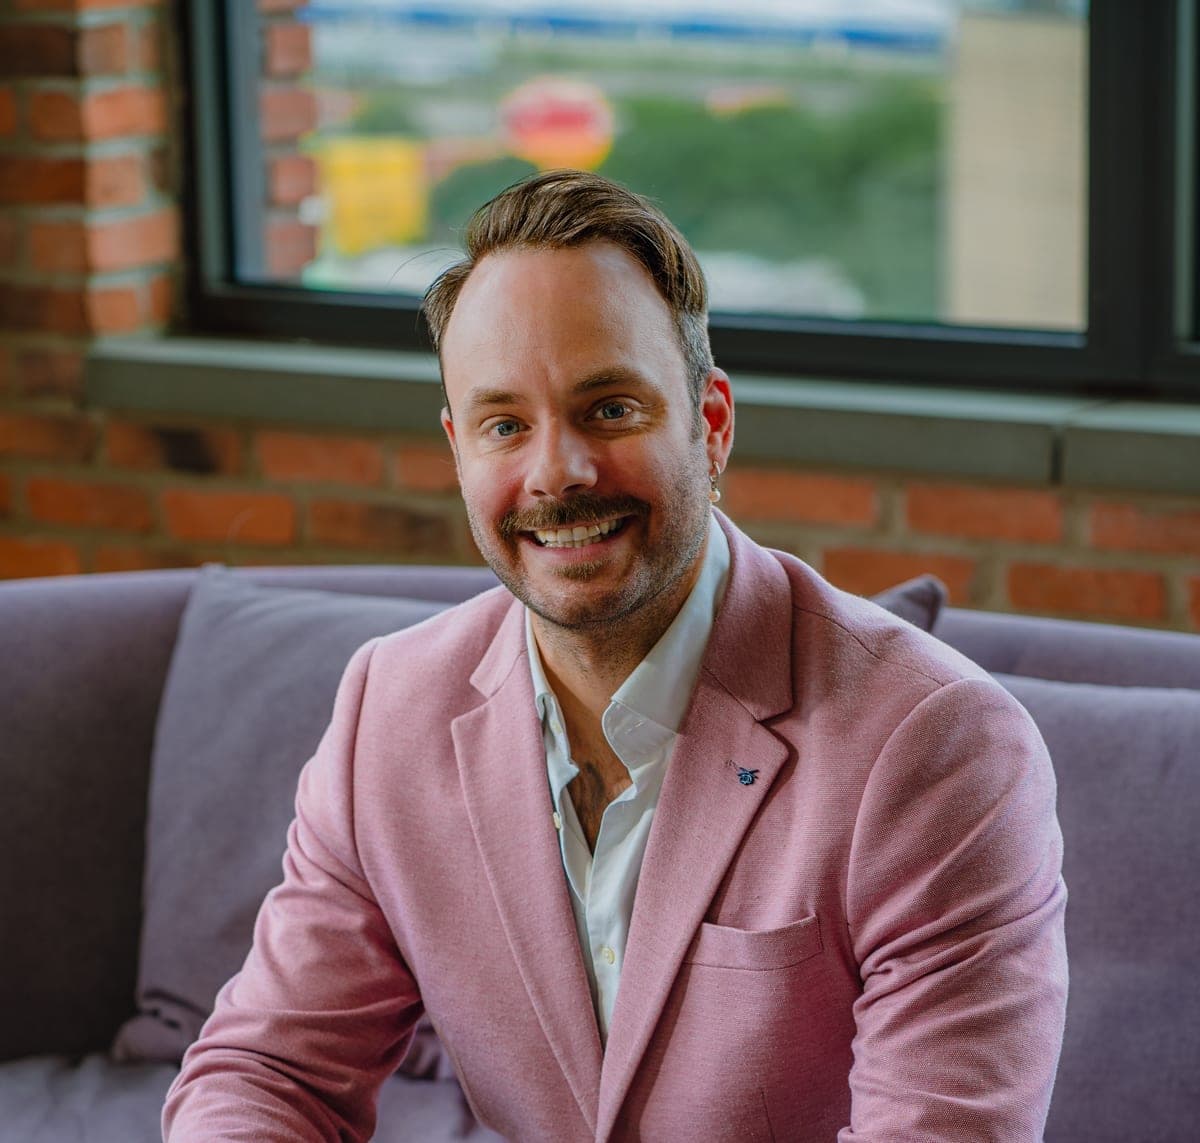
SMBs and corporate
Explanation of the possible ownership structures for critical illness, taking the tax context into account.
Vulnerability analysis
Alexandre identifies your key people and quantifies the financial impact of their prolonged absence.
Accountant coordination
Work with your accountant on the tax treatment of the capital received by the company and how it is used.
Annual review
Updating coverage based on your business's growth and the evolution of your leadership team.
Alexandre Garneau, Financial Security Advisor, Services Financiers AG.
SMB
Corporate protection
COMPARISON

With or without corporate protection

No protection
Personal policy only
Corporate critical illness
RECOMMENDED
Capital to the company on diagnosis$0NoneAmount set by contract
Continuity of operations fundedNoNoYes
Temporary replacement fundedNoNoYes
Cash flow protectionNoNoYes
Choice of ownership structureNoPersonal onlyDepends on your structure
Complementary to the personal policyNoN/AYes
Choose this strategy
STRUCTURE FACTORS

How to structure
your protection?

The right structure depends on your business. Alexandre analyzes each variable with you.

Analyze my business
Number of illnesses covered
Basic or extended coverage, depending on the product

A company-owned policy is generally the same product as a personal policy: only the owner and beneficiary change. Alexandre selects the appropriate coverage based on the risk profile of the leaders to be insured.

Profile of the insured persons
Age, health, family history

Each leader or key employee is assessed individually. The premium depends on the age and health of each insured person - Alexandre prepares a quote for each profile.

Amount of capital to protect
Based on the person's operational value

The capital is calibrated based on the replacement cost of the key person: replacement salary, recruitment costs, estimated lost revenue and the length of the transition period. Alexandre uses a structured framework.

Ownership structure
Corporate or personal?

The choice has tax consequences: who pays the premium, who receives the capital and how it can then be paid to shareholders. Unlike life insurance, a critical illness benefit received by the company does not create a CDA credit. Alexandre coordinates with your accountant to choose the right structure.

PROCESS

How do you file a claim?

Alexandre coordinates the process for your business.

01
Diagnosis

Once medically confirmed, notify the insurer with the attending physician's report.

As soon as possible
02
Documentation

Claim form, medical certificate and policy statement.

Alexandre coordinates
03
Processing

The insurer reviews the file. The survival period set out in the contract applies (often 30 days).

Timeline varies by insurer
04
Payout

Capital paid to the company according to the policy designation.

Free use
COMPLETE YOUR STRATEGY

Related products

YOUR QUESTIONS

Frequently asked questions

What's the difference between a corporate and personal critical illness policy?

A personal policy pays the capital to the insured person for their personal needs. A corporate policy pays the capital to the company to protect operations. The two can coexist and complement each other. Alexandre analyzes which combination matches your situation.

Is the capital paid to the company taxable?

A critical illness benefit received by a company is generally considered non-taxable, but no specific tax rule governs it. Unlike a life insurance death benefit, it is not credited to the Capital Dividend Account (CDA): if the company then pays it to shareholders, it will generally be a taxable dividend. Alexandre coordinates with your accountant based on your structure.

Should all leaders be insured or only the key person?

It depends on the structure of your leadership team. In a company with two partners, it often makes sense to cover both. For a business that depends on a sales director, a targeted key person policy may be enough. Alexandre analyzes the vulnerability of each role.

Can the capital be used for purposes other than operations?

Yes. Once paid, the capital from a company-owned critical illness policy can generally be used freely. The company can allocate it to its needs: replacement, debt, projects, or a cash reserve.

Which illnesses are covered in the corporate version?

The same as personal policies of the same product, for example cancer, heart attack, stroke, organ transplant or multiple sclerosis, as defined in the contract. The number of illnesses covered varies by product.

Is the premium deductible for the company?

Generally, no: a critical illness premium paid by the company is not deductible. If the company pays the premium on a policy whose beneficiary is a shareholder or employee, it may create a taxable benefit for that person. The tax treatment depends on your structure, to confirm with your accountant.

Does the survival period also apply to the corporate version?

Yes, the survival period set out in the contract also applies (often 30 days after diagnosis). Alexandre checks the specific clauses for the product chosen for your business.

What happens if the key leader leaves the company?

The policy can be transferred to the person, cancelled, or reassigned to a new key leader. A transfer can have tax consequences. Alexandre reviews the structure whenever the leadership team changes.

GOOGLE REVIEWS

What clients say

5.0 on Google · 10 reviews
“Thanks to Alexandre for the great advice on protecting myself and my business! I wasn't aware of all the insurance options available for my company.”
Ana Maria DanuletGoogle review · · Translated by Google
“Thank you for the advice regarding my business insurance.”
Marc-AndréGoogle review · · Translated by Google
“Excellent service from start to finish. Alexandre is very professional, attentive, and takes the time to explain the different options without putting any pressure on me. I felt well-advised and confident throughout the entire process. I highly recommend AG Financial Services.”
Anthony DussaultGoogle review · · Translated by Google

Reviews posted by clients on the Services Financiers AG Google listing, in French; the English text is Google's automatic translation. Every situation is different: a review does not predict the outcome of yours.

LET'S TALK

Protect your business against
the medical unexpected.

Alexandre analyzes your key people and offers a suitable corporate strategy. Free, no obligation.

Reply within 48h
Coordination with your accountant
AMF certificate no. 272275

An email or a phone number is enough.

Confidential. Used only to answer your request.